
BMBI August year-on-year value sales up +0.5%, but volumes down -5.4%
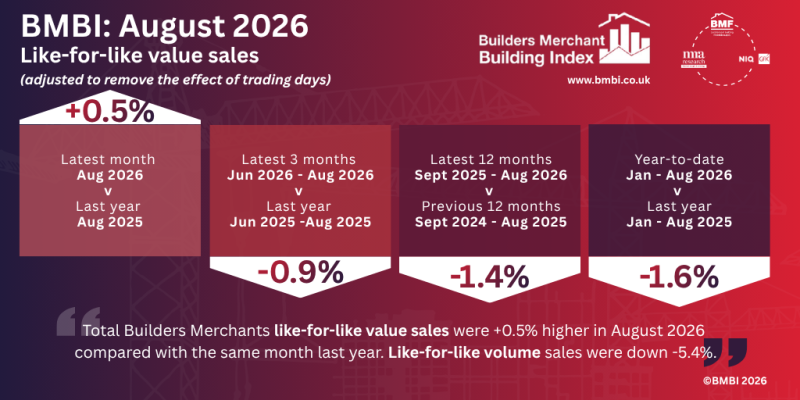
The latest Builders Merchant Building Index (BMBI) report, published in October, shows August’s total like-for-like value sales (adjusted to remove the effect of trading days) were up +0.5% compared to August 2025. Year-on-year like-for-like volume sales were down -5.4%, while prices increased +6.2%.
With no difference in trading days, August’s unadjusted value sales were also +0.5% higher than the same month a year before. Unadjusted volumes were down -5.4% and prices up by +6.2%. By value, nine of the twelve categories sold more with Workwear & Safetywear (+22.8%) the standout category. Timber & Joinery Products (+0.7%) made marginal gains, while the largest category, Heavy Building Materials eased -0.8%. Ironmongery (-1.5%) and Tools (-0.6%) were the weakest categories.
In the three months June to August, like-for-like value sales were -0.9% lower than the same three-month period in 2025. Like-for-like volume sales were down -7.7% and prices increased +7.4%.
With one additional trading day in the most recent three-month period, unadjusted value sales rose +0.7% compared to the same three months in 2025. Unadjusted volumes decreased -6.3% and prices increased +7.4%. By value, seven categories sold more, led by Workwear & Safetywear (+17.4%) and Services (+9.1%). Of the two largest categories, Timber & Joinery Products (+1.0%) increased more than Total Builders Merchants, while Heavy Building Materials was down -1.0%. Plumbing, Heating & Electrical (-1.6%) was the weakest category.
In the 12 months September 2025 to August 2026, like-for-like value sales were -1.4% down compared to the previous 12-month period (September 2024 to August 2025). Like-for-like volume sales were down -5.5%, while prices were up +4.3%.
With one extra trading day in the most recent 12-month period, unadjusted value sales were -1.0% lower year-on-year. Unadjusted volume sales declined -5.1% and prices increased +4.3%. By value, seven categories sold more, with Renewables & Water Saving (+7.0%) the strongest category. Timber and Joinery Products was up +1.1% but Heavy Building Materials was the weakest category (-3.3%).
In the year to date (January to August), like-for-like value sales were -1.6% lower compared to the first eight months of 2025. But like-for-like volume sales were down -7.2% and prices were up +6.0%. With no difference in trading days, unadjusted value sales were also down -1.6%, as volumes fell -7.2% and prices increased +6.0%. By unadjusted value, half the categories sold more with Workwear & Safetywear (+9.5%) growing the most. Timber & Joinery Products (+0.3%) performed better than Total Builders Merchants, but Heavy Building Materials (-3.9%) was again the weakest category.
Mike Rigby, Managing Director of MRA Research which produces the BMBI report says: “It’s tough out there, as BMBI and the latest ONS construction data confirm. Construction output has fallen for four consecutive months, down -0.2% in August. The ONS has revised its July output figure of +0.1% up to -0.5% down as more data became available. Private housebuilding’s output has dropped -3.2% over the past three months, and down -1.9% in August, is depressing total construction output.
“If you’re from outside the industry, these numbers can wash over you. But, as Professor Noble Francis, Economics Director of the CPA, comments, ‘The Bank of England reported 54,918 mortgage approvals in August. This was 1.8% lower than in July and 16.0% lower than a year ago. Approvals in August were also 21.0% lower than in January 2020, pre-pandemic. Year-to-date, UK mortgage approvals in 2026 were 7.1% lower than last year and 27.5% lower than the recent peak in 2021.’
“Housing is getting a hammering,” Rigby continues, “further encumbered by extra costs and regulations casually imposed by Government – the House Builders federation calculates they add an extra £38,030 to the average cost of a new build home – but the UK economy is showing remarkable resilience. The latest ONS figures suggest GDP increased +0.1% in August. Annually, the economy has grown +2.1% – it’s strongest rate since August 2022. The IMF’s latest forecast puts Britain’s growth equal second among the G7 group of advanced economies, after the US economy which is storming. Our national media and politicians are so used to talking Britain down that they’re surprised by such confidence in the UK.
“Fortunately, the public is more positive and resilient. The GfK Consumer Confidence Index showed a 1-point increase to -13 in September, marking a third month of consecutive improvement for the first time since 2024. A lot is riding on the Autumn budget, which will determine whether consumers and businesses feel better or worse off under the new Prime Minister. Good or bad, the ripples will be felt throughout construction.”
Set up and run by MRA Research, the BMBI – a brand of the Builders Merchants Federation – is a monthly index of builders’ merchant sales, and the most reliable, up-to-date measure of Repair, Maintenance, and Improvement (RMI) activity in the UK. The index is based on actual sales from NiQ GfK’s Builders’ Merchant Point of Sale Tracking Data, which captures value sales out to builders from generalist builders’ merchants, accounting for 88% of total sales from builders’ merchants throughout Great Britain. An in-depth review, which includes commentary by sector experts, is provided each quarter.