
A -0.6% fall in July Merchant value sales year-on-year, but volumes drop -7.6%
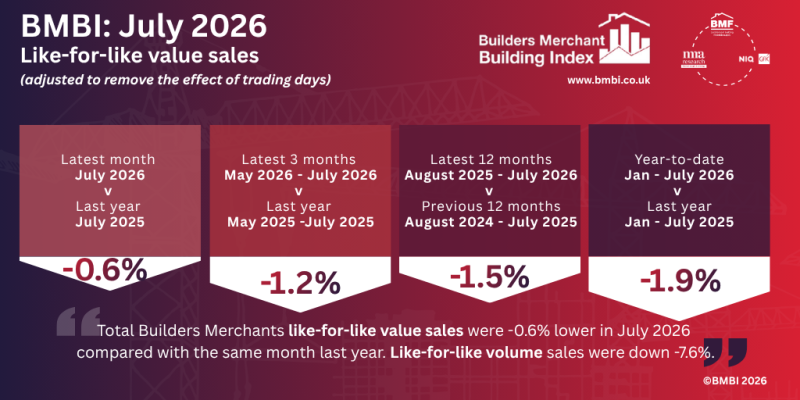
The latest Builders Merchant Building Index (BMBI) report, published in September, shows July 2026’s total like-for-like value sales (adjusted to remove the effect of trading days) were -0.6% lower than July 2025. Like-for-like volume sales were down -7.6% year-on-year.
With no difference in trading days, July’s unadjusted value sales were also -0.6% lower compared to the same month in 2025. Volumes were down -7.6% and prices increased +7.6%. By value, half of the twelve categories sold more with Workwear & Safetywear (+18.5%) and Services (+7.7%) the standout categories. Plumbing, Heating & Electrical (-4.6%), Tools (-2.5%) and Renewables & Water Saving (-2.4%) were down, with both the largest categories, Timber & Joinery Products (-0.7%) and Heavy Building Materials (-2.6%) selling less.
In the three months May to July, like-for-like value sales were -1.2% lower than the same three-month period in 2025. Like-for-like volume sales were down -8.0% and prices increased +7.4%. With no difference in trading days, unadjusted value sales were also down
-1.2%, with volumes decreasing -8.0% and prices increasing +7.4%. By value, only four categories sold more, led by Workwear & Safetywear (+12.5%) and Services (+7.6%). Of the two largest categories, Timber & Joinery Products (-0.7%) fell less than Total Builders Merchants, while Heavy Building Materials (-2.8%) fell more. Renewables & Water Saving(-4.7%) was the weakest category.
In the 12 months August 2025 to July 2026, like-for-like value sales were down -1.5% compared to the previous 12-month period (August 2024 to July 2025). With no difference in trading days, unadjusted value sales were also -1.5% lower year-on-year, while volume sales declined -5.0% and prices rose +3.7%. By value, seven categories sold more, with Renewables & Water Saving (+7.2%) performing best. Of the two largest categories, Timber and Joinery Products grew +0.8% while Heavy Building Materials slipped -3.8% and was weakest overall.
In the year to date (January to July), like-for-like value sales were -1.9% lower than the first seven months of 2025. Like-for-like volume sales were down -7.4 % and prices were up +5.9%. With no difference in trading days, unadjusted value sales were also down -1.9%, as volumes fell -7.4% and prices increased +5.9%. By total unadjusted value, six categories sold more with Workwear & Safetywear (+7.8%) growing the most. Timber & Joinery Products (+0.2%) performed better than Total Builders Merchants, while Heavy Building Material (-4.3%) was the weakest category again.
Mike Rigby, Managing Director of MRA Research which produces the BMBI report says: “It will have come as a shock to no-one in the construction industry to hear Housing Secretary Angela Rayner recently confirm that there was only a ‘slim chance’ the government would deliver on its pledge to deliver 1.5 million homes during its 5-year term.
“While adding that she was not giving up completely on the ‘stretch target’, even the Government’s new – still undefined – plan to boost social and affordable housing construction is unlikely to bring the number of new dwellings even close to hitting 300,000 a year. Savill’s latest predictions put new home completions closer to an average of 167,500 a year up to 2029/30, a long way short of the mark.
“And there’s not much in the pipeline either. The latest ONS data shows that total construction output grew by +0.1% in July, marginally bucking the trend of decreases in June (-0.1%) and May (-0.8%). This was driven by repair and maintenance (+0.8%) as new work fell by -0.4%. The main contributor to the decrease in new work – private housing – was down -4.9%.
“With the budget barely a month away, and the Government tight lipped about its content after 2025’s ill-fated December budget, it’s difficult to know whether John Healey’s red box will contain any rescue lines for housebuilding. The industry is calling for a raft of support – like what has already been put in motion for hospitality – to try and get Britain building, and people buying and moving again. Will the SOS be heard?”
Set up and run by MRA Research, the BMBI – a brand of the Builders Merchants Federation – is a monthly index of builders’ merchant sales, and the most reliable, up-to-date measure of Repair, Maintenance, and Improvement (RMI) activity in the UK. The index is based on actual sales from NiQ GfK’s Builders’ Merchant Point of Sale Tracking Data, which captures value sales out to builders from generalist builders’ merchants, accounting for 88% of total sales from builders’ merchants throughout Great Britain. An in-depth review, which includes commentary by sector experts, is provided each quarter.
Set up and run by MRA Research, the BMBI – a brand of the Builders Merchants Federation – is a monthly index of builders’ merchant sales, and the most reliable, up-to-date measure of Repair, Maintenance, and Improvement (RMI) activity in the UK. The index is based on actual sales from NiQ GfK’s Builders’ Merchant Point of Sale Tracking Data, which captures value sales out to builders from generalist builders’ merchants, accounting for 88% of total sales from builders’ merchants throughout Great Britain. An in-depth review, which includes commentary by sector experts, is provided each quarter.